


Ditch: Pay Off Debt Faster
4.862.00 Reviews
App Specs
- Version
- 1.5.6
- Updated On
- License
- Free
- Downloads
- 10,000+
- Developer
- Ditch Technologies, Inc
- Categories
- Finance
- Platform
- Android
Screenshots
 Analysis by AppCompare
When I look at a debt tracker, I care about more than a payoff chart: I want to know whether it fits the moments when I actually make money decisions. Ditch: Pay Off Debt Faster is a finance app from Ditch Technologies, Inc, built around organizing balances and keeping a payoff plan visible. That focus can be useful when several debts compete for attention, but it also means the app works best as a planning companion, not a substitute for checking statements or making payments through your lenders.
Where a connection matters most
The key moments in a debt app are often the ones when I need to enter or revise information: adding an account, changing a balance, or adjusting what I can pay. Because those details drive the plan, I’d make updates when I have a stable connection and enough time to check the numbers against current statements. I would not treat a displayed payoff estimate as current if I have since made a payment or my lender has changed the balance.
That distinction matters in everyday use. A tracker can help me see the consequences of a choice, such as putting extra money toward one balance rather than splitting it, but the lender remains the source for the amount due and payment status. I’d use Ditch to think through the plan, then confirm the actual payment in the relevant account. Keeping those roles separate avoids the common mistake of assuming that recording a payment in a planner has sent money to a creditor.
Useful on a phone, with a little preparation
Debt decisions rarely happen only at a desk. I might check the plan while waiting for a bill to load, after reviewing a household budget, or before deciding whether a nonessential purchase can wait. Ditch is most helpful in those quick checks when I have already entered reasonably accurate figures; building a full debt picture while distracted or rushing is more likely to create mistakes than clarity.
My practical tip is to gather balances, interest rates, minimum payments, and due dates before setting up a payoff plan. Then I can enter information deliberately instead of switching between apps or statements repeatedly. I’d also choose a regular review time—perhaps when I go through monthly bills—so the plan reflects meaningful changes without turning debt tracking into a daily source of worry.
What to do when numbers change
Unexpected expenses, variable income, and revised statements can all make a payoff plan stale. If a number looks wrong or an update does not appear as expected, I would first check the source statement, confirm the entry I made, and review the plan again when the connection is reliable. I would avoid making a financial decision based only on an old screen or an estimate I have not checked.
This is also where a manual tracker has a trade-off: entering figures takes effort, but it encourages me to look directly at each balance instead of assuming everything is current. I would keep a simple record of the date I last reviewed the figures, especially if I’m comparing strategies over time. If the app’s current view does not match a lender’s account, I’d trust the lender for the account balance and use the tracker only after correcting my own planning inputs.
Worth Reading Before You Choose

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy

ESPN’s Live Game View Makes Following Close Games Easier
Using it without oversharing or overchecking
Financial information deserves care. I’d enter only what I need to make a useful plan and avoid using a shared or public device for personal money details. I would also read the app’s current privacy and account information before deciding how much to record, rather than assuming that every finance app handles data in the same way.
There is a behavioral trade-off, too: frequent checking can make progress feel more dramatic, but balances do not necessarily change every day. For me, a scheduled review is more useful than opening a debt tracker whenever I feel anxious. That keeps the numbers actionable and makes it easier to focus on the next payment instead of treating every small fluctuation as a verdict on my finances.
Who will get the most from it?
I see Ditch as a good fit for someone with multiple balances who wants a clearer order of attack and is willing to keep the figures current. It can also help a couple or household discuss priorities, provided they agree on the numbers and use the app as a shared planning aid rather than as proof that a particular choice is automatically right.
Someone with one straightforward balance and a fixed repayment routine may get enough from a lender’s own account tools or a simple spreadsheet. A person who expects every balance to update automatically, needs the app itself to execute payments, or prefers detailed forecasting may want to compare other tools before committing to a workflow. The important question is not whether a chart looks motivating; it is whether maintaining the underlying figures feels manageable.
A realistic example: after payday, I could check the latest statements, update the balances, and see whether an extra amount is better directed toward the highest-rate debt or a smaller balance I want to clear first. Before paying, I’d confirm each lender’s minimum and due date, leave room for essential expenses, and then make the payment through the lender. That small routine turns a general goal into a decision without pretending the app controls the whole process.
Compared with a spreadsheet, a dedicated tracker can make the payoff picture easier to scan and may feel less like building a tool from scratch. A spreadsheet offers more freedom to model unusual income or custom rules, but it asks me to maintain the layout and formulas. Compared with a bank or lender app, Ditch is aimed at seeing debts together rather than managing one creditor’s account. I’d use the lender’s app for authoritative account activity and a broader planner for the cross-debt view.
There are a few practical questions I’d settle before relying on it. Can I keep my preferred payoff strategy aligned with changing income? How much time will it take to update balances? Is the level of detail comfortable for everyone who may see my phone? Those answers depend on a person’s routine, so I’d start with a small set of debts and see whether the upkeep is worthwhile before building the app into every financial decision.
The app is free to download, with in-app purchases listed from $8.99 to $89.99 per item, so I’d check what any optional purchase includes before paying. It is rated for Everyone, has a 4.1 average from around 96 ratings, and has over 10K installs. Version 1.4.1 supports Android 8.0 and later. Those details place it within reach for many Android users, while the purchase range is a reason to review the available options rather than assume every tool is included at no cost.
For me, the best way to judge Ditch is to use it for a real planning cycle: enter verified figures, choose a strategy that fits my motivation and interest costs, then revisit the plan when I next review bills. If the routine helps me make a clear next move without adding stress, it earns a place on my phone. If I need automated account syncing or a full payment service, I’d look for a tool built around those needs instead.
Getting Started with Ditch
So, here’s how it works. You download Ditch: Pay Off Debt Faster, available on both Android and iOS, and set it up in a jiffy. The user interface is pretty clean and straightforward, which is a massive relief when you’re already stressing about money. You start by entering your debts—credit cards, student loans, mortgage, you name it.
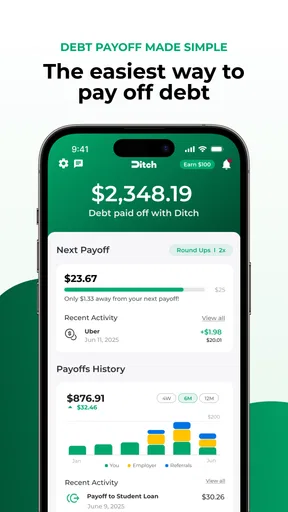
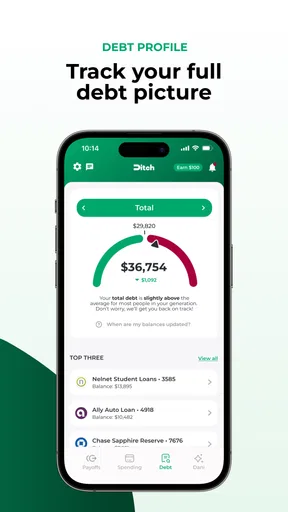
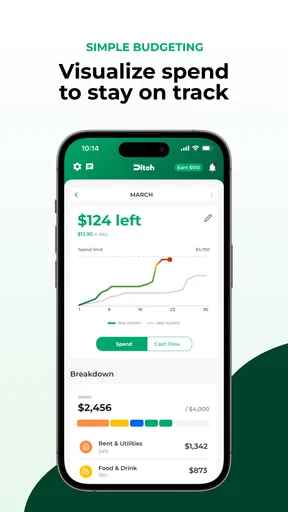
You’ll love how the app visualizes your debt landscape. It’s got these colorful graphs and charts that lay it all out for you, making it super easy to understand where you stand financially. Trust me, seeing your debt in such a clear format is both terrifying and motivating!
Features That Stand Out
Personalized Payoff Plans: This feature is a game-changer. The app suggests personalized strategies to tackle your debt. Whether you prefer the avalanche method (tackling high-interest debts first) or the snowball method (paying off smaller debts first), Ditch has got you covered. You can even customize your payoff plan to suit your financial goals.
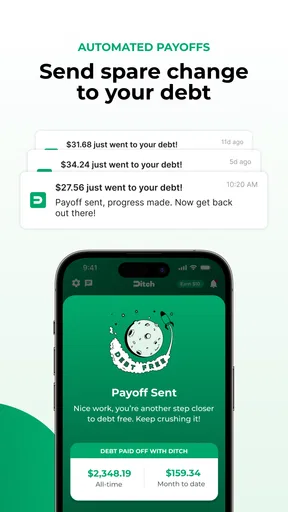
Progress Tracking: Nothing feels as good as watching your debt shrink right before your eyes. The progress tracker is incredibly satisfying. Each payment you make is a step closer to financial freedom, and the app celebrates those little victories with you.
Budgeting Tools: Ditch doesn’t just help you pay off debt; it also assists in managing your finances better. The budgeting tools are intuitive and allow you to allocate funds effectively, ensuring that you don’t fall back into that dreaded debt cycle.
Is It Worth the Download?
Now, let’s talk about whether it’s worth making room for this app on your phone. Honestly, if you’re serious about paying off your debt faster, Ditch is absolutely worth it. The app is designed to help you stay focused and motivated, and it does just that. Plus, the satisfaction of seeing your debt diminish over time is priceless.
Of course, the app isn’t perfect. It requires a bit of discipline and honesty while entering your financial details. But once you’re on board, it becomes a trusty companion on your debt-free journey.
Final Thoughts
At the end of the day, Ditch: Pay Off Debt Faster offers more than just a way to manage debt. It’s a financial ally that guides you towards a healthier financial future. The app is all about empowerment, giving you the tools you need to take control of your debts and ultimately, your life.
So, if you’re ready to tackle your debt head-on and want an app that makes the process a tad bit easier, Ditch might just be your perfect match. Go ahead, give it a try, and watch your financial worries start to melt away.
Pros
- User-friendly interface simplifies tracking
- Customizable payment plans for flexibility
- Real-time updates on debt progress
- Secure encryption for data protection
- Integrates with multiple bank accounts
Cons
- Limited support for international currencies
- No offline access to features
- Subscription fee required for premium tools
- Doesn't support joint account tracking
- Occasional sync issues with banks
FAQs for Ditch: Pay Off Debt Faster
What is Ditch: Pay Off Debt Faster?
Ditch: Pay Off Debt Faster is a personal finance app designed to help users manage and pay off their debts more efficiently. By offering tailored strategies, tracking tools, and motivational features, the app aims to simplify the debt repayment process and reduce the time it takes to become debt-free.
How does Ditch help in managing debts?
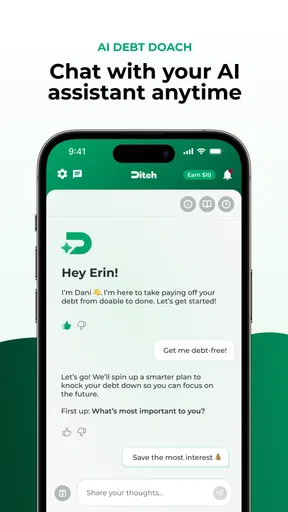
Ditch provides users with personalized debt repayment plans based on their financial situation. The app analyzes your debts and income, suggesting the most effective payment strategies, such as the snowball or avalanche methods. It also tracks progress, offering insights and reminders to keep you motivated and on track.
Is Ditch secure to use with my financial information?
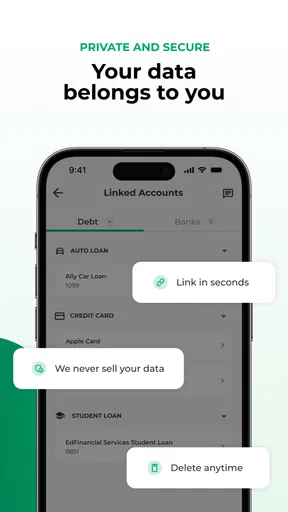
Yes, Ditch is designed with user security in mind. It employs industry-standard encryption to protect your data and ensure that your personal and financial information remains confidential. Regular security updates and protocols are in place to safeguard your information against unauthorized access.
Can I link multiple accounts to Ditch?
Absolutely, Ditch allows you to link multiple financial accounts, such as credit cards, loans, and bank accounts, to provide a comprehensive overview of your debt situation. This feature helps in tracking all your liabilities in one place, making it easier to manage and repay them efficiently.
Is Ditch available for both Android and iOS?
Yes, Ditch is available for download on both Android and iOS platforms. The app can be found in the Google Play Store for Android users and the Apple App Store for iOS users, ensuring accessibility for a wide range of smartphones and tablets.


